
lonnyijr738125
About lonnyijr738125
Sexy Listing
There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
Home prices at the national level have stayed stubbornly high even as financing costs doubled in under two years. The reason is supply. Homeowners who locked in three percent mortgages in 2020 and 2021 have almost no incentive to sell, which means the correction that many analysts were expecting simply did not materialize the way the data suggested it should.

Before you look at a single listing, get your pre-approval locked down. Not a rough estimate. Not a verbal confirmation from a loan officer you met once. A full pre-approval based on verified income, tax returns, bank statements, and a hard credit pull. In this market, a seller who receives an offer without that documentation will not take it seriously.
 If the report surfaces problems that go well beyond normal wear and tear, you have real choices, and walking away is a legitimate one of them. You can ask the seller to repair specific items before closing. What you should not do is panic and waive your right to negotiate.
 Budget two to four percent of the purchase price for closing costs, on top of your down payment. First-time buyers often do not see the full closing cost picture until the Closing Disclosure arrives three days before settlement. Ask your lender for a Loan Estimate as early in the process as possible.
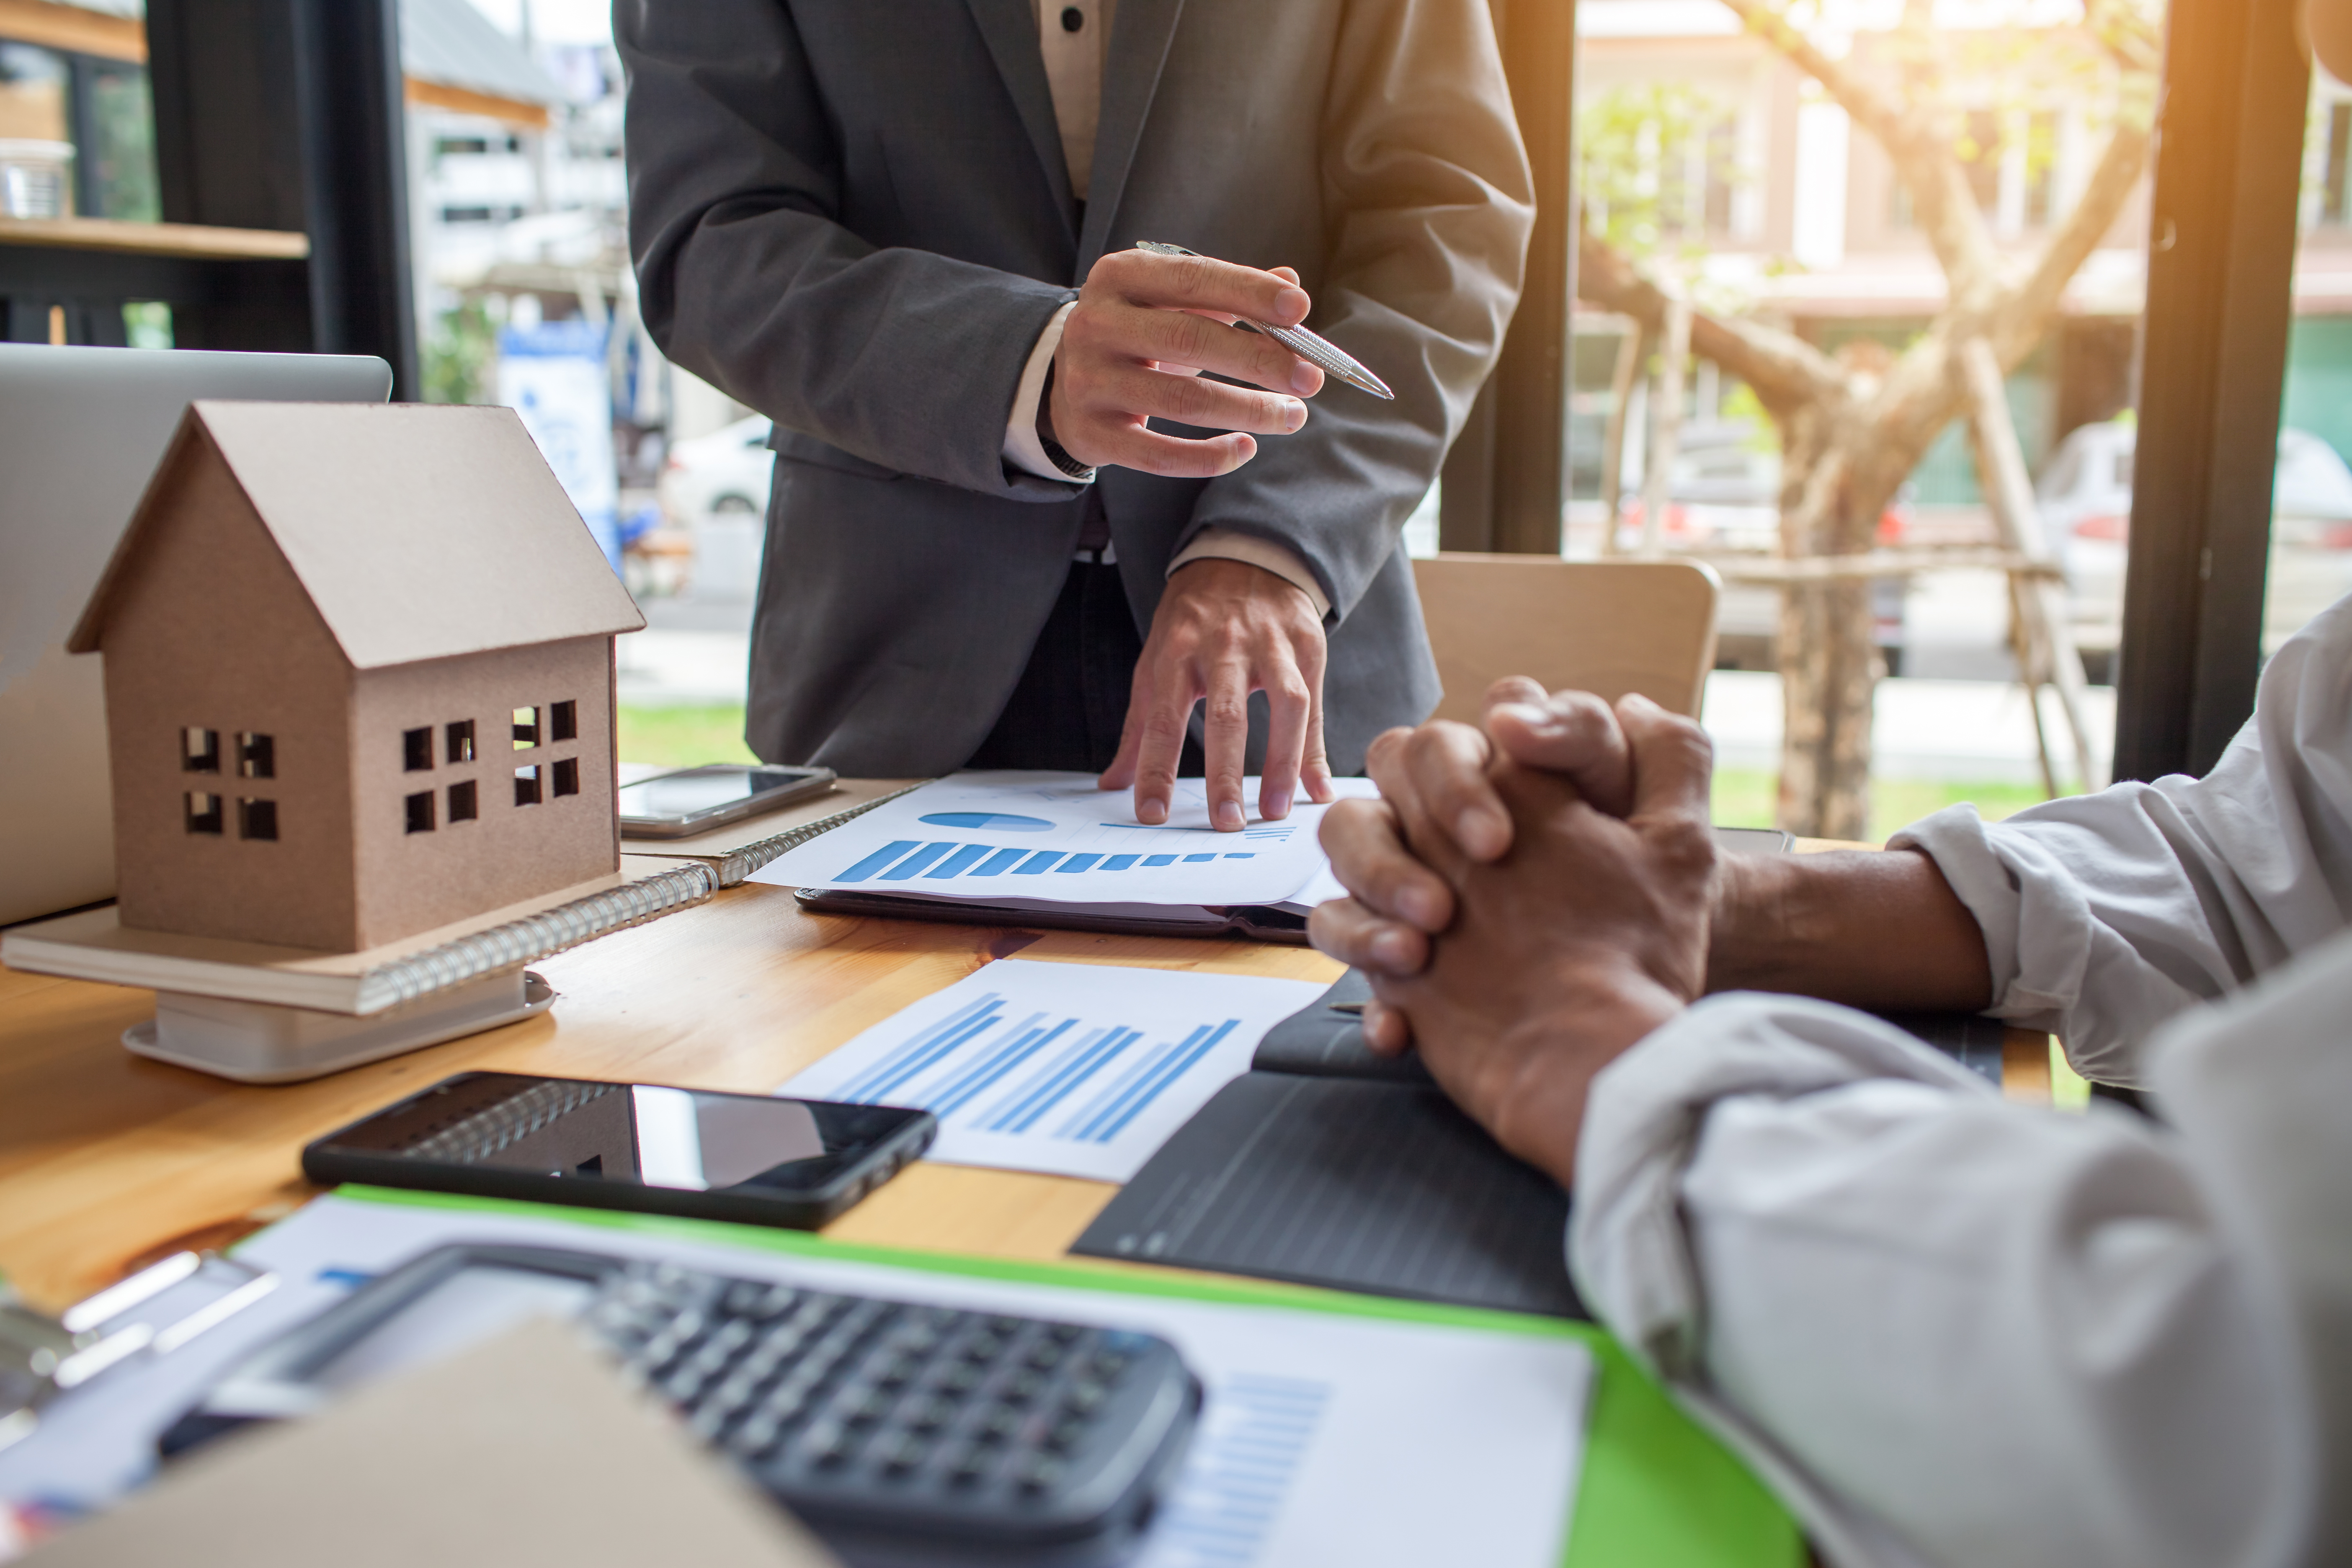 The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. Waiting for the perfect moment is how people end up renting for another five years when they did not mean to. The more useful question is not whether now is the right time in the abstract; it is whether the home works for your actual life for the next five to seven years.
 The buyers who come out ahead in this market are not the ones who waited for perfect conditions. They are the ones who understood what they could afford and moved with confidence. The most useful thing you can do today is look at homes for sale near you and see whether the numbers work for your situation.
No listing found.